Is it smarter to rent a home or buy property in California right now? Deciding whether to keep paying your landlord or to take out a multi hundred thousand dollar mortgage is one of the biggest financial crossroads you will ever face. In the Golden State, where real estate feels like a competitive sport, a mistake can cost you hundreds of thousands of dollars. Many people believe renting is just throwing away money, while others argue that buying a home at today’s prices is a fast track to financial stress. To find out which option makes true financial sense for you, you need to look past real estate sales pitches and dive deep into the actual mathematical calculations, state tax frameworks, and historical market metrics.
1. The Current State of the California Housing Affordability Index
To understand why the choice between renting and buying is so intense right now, we have to look at supply and demand. The California Association of Realtors (C.A.R.) tracks a specific metric known as the Housing Affordability Index (HAI). This index measures the percentage of households in the state that earn enough income to qualify for a mortgage on a median priced, single family home. According to official C.A.R. market data, California’s housing affordability index sits at approximately 22%. This means that roughly 78% of California families are mathematically priced out of purchasing a median detached home, which hovers around $843,390 statewide.
To qualify for a standard 30 year fixed mortgage at current interest rates near 6.24%, a buyer needs a minimum annual income of at least $204,800 just to handle the estimated monthly payment of $5,120 (inclusive of principal, interest, taxes, and basic insurance). If your household income falls below this threshold, renting is often your primary entry point into the California market
2. Monthly Mortgage vs Rent, The Real World Cost Comparison
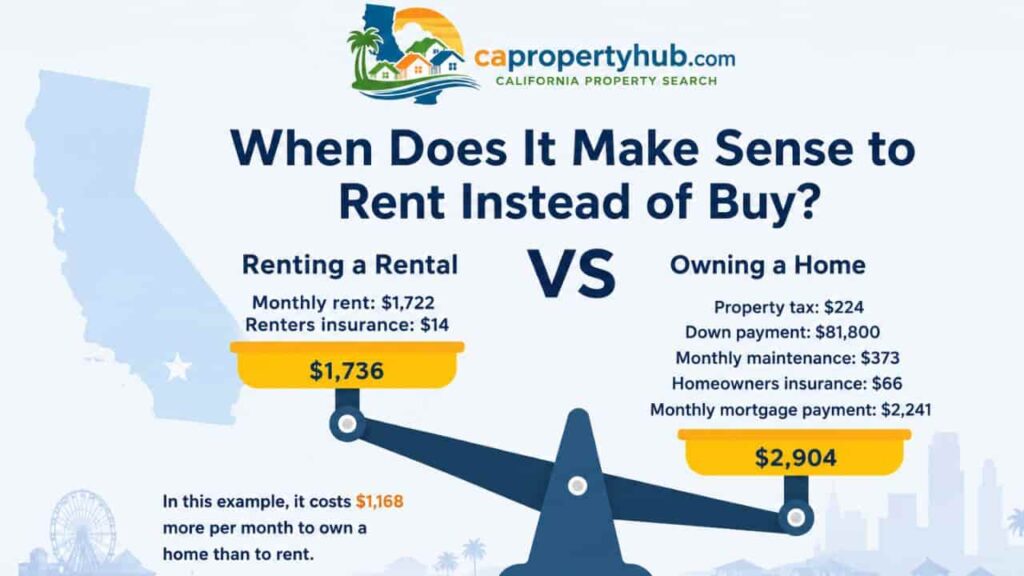
When evaluating renting vs buying property California, your immediate concern is your monthly cash flow. Across every single major metropolitan area in California from the Silicon Valley tech hubs to coastal Southern California,. There is a dramatic gap between average rent prices and standard monthly mortgage payments.
Analyzing the California Payment Premium
Data from statewide rental indices shows that the median asking rent in California sits around $2,750 per month. However, because home prices are at record highs, buying a starter home in the same regions requires a massive monthly premium.
- San Jose & San Francisco
In these ultra premium Bay Area markets, renting is significantly cheaper on a monthly basis. Buying a median priced home can demand a monthly mortgage payment that is over $2,100 to $4,000 higher than the local median rent for an equivalent property. - Los Angeles & San Diego
Southern California tells a similar story. The average monthly mortgage payment on a newly purchased single family home sits between $4,300 and $6,500, while median monthly rents hover between $2,800 and $3,000.
Expert Insight. From a pure short term monthly cash flow perspective, renting currently leaves you with more disposable income in California than buying. However, cash flow is only one piece of the long term wealth equation.
3. The Math Behind Local Rental Yields
Professional real estate investors use a specific mathematical formula to determine whether a market is overvalued or if it favors renting over purchasing. This calculation is known as the Gross Rental Yield.
Gross Rental Yield = Annual Rental Income / Total Property Purchase Price x 100$$
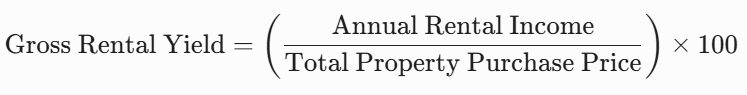
When rental yields across a state are exceptionally low, it tells you that home prices have grown significantly faster than rental rates, heavily tipping the financial scales in favor of renting.
California Metro Affordability & Cash Flow Matrix
To visualize how these numbers play out across different regions of the state, review this real world market matrix compiled from localized housing registries and rental indices.
| California Metro Area | Median Home Purchase Price | Median Monthly Rent Rate | Average Monthly Mortgage Payment |
| San Jose / Silicon Valley | $1,387,000 | $3,406 | $7,500 |
| San Francisco Bay Area | $1,340,000 | $3,064 | $5,242 |
| Los Angeles Metro | $1,005,000 | $2,885 | $4,538 |
| San Diego County | $949,900 | $2,871 | $4,345 |
| Sacramento Region | $485,000 | $1,842 | $2,644 |
4. Equity Building and Long Term Wealth Accumulation
If renting is so much cheaper month to month, why does anyone still buy property in California? The answer lies in long term wealth generation and equity building. When you pay $2,750 in rent every month, 100% of that capital is gone forever. Over a five year period, a California renter sends roughly $165,000 to their landlord, yielding a 0% return on investment.
How Homeowners Build Wealth
- Principal Paydown
A portion of every monthly mortgage payment goes toward reducing the principal balance of your loan, acting as a forced savings account that slowly builds ownership equity. - Property Appreciation
Historically, California real estate values appreciate over the long term. Even at a modest annual appreciation rate of 3%, an $800,000 home gains $24,000 in equity value in just twelve months. Over 10 to 20 years, this compounding growth creates substantial net worth that renters entirely miss out on.
5. Maximizing Tax Benefits, The Property Tax Deduction Framework
Another major pillar of homeownership is the unique collection of tax write offs provided under both federal and state tax codes.
The Mortgage Interest Deduction (MID) Limits
Under current Internal Revenue Service (IRS) guidelines, federal tax law allows homeowners to deduct the interest paid on the first $750,000 of their home acquisition debt. In high priced California markets, this deduction can provide a massive reduction in your annual taxable income during the early years of your loan, when your payments are heavily weighted toward interest.
State Tax Advantages
- Property Tax Deduction
Homeowners can write off local property taxes up to a maximum cap of $10,000 under the federal State and Local Tax (SALT) deduction limits. - Capital Gains Exclusion
When it comes time to sell your primary residence, Section 121 of the internal revenue code allows individuals to exclude up to $250,000 (and married couples up to $500,000) of real estate capital gains from their federal taxes, provided they lived in the home for two out of the past five years.
6. Step by Step Decision Checklist for Californians
If you are trying to determine whether to sign a new lease or apply for a pre approval letter, execute this analytical step by step decision framework.
- Step 1. Calculate your debt to income (DTI) ratio to confirm your household income satisfies the housing affordability index requirements.
- Step 2. Determine your target residency timeline. If you plan to relocate out of the area in less than 5 years, the upfront closing costs of buying will likely outpace your short term equity building.
- Step 3. Calculate the exact monthly price premium (Mortgage Cost minus Rent Cost) for your specific neighborhood.
- Step 4. Estimate your potential tax savings by running your numbers against federal property tax deduction and mortgage interest limits.
- Step 5. Assess your liquid cash reserves to ensure you have a 20% down payment plus an emergency reserve to cover rising home insurance premiums across the state.
Final Expert Verdict
The financial choice between renting and buying in California comes down to your personal investment timeline. If you plan to live in a city for less than five years, renting is highly rational because it protects your liquid capital from heavy transactional friction. However, if you plan to stay long term, buying property is the superior tool for building household wealth, protecting you from future rent inflation while securing stable federal tax advantages.
FAQs
Is it cheaper to rent or buy in California right now?
On a month to month cash flow basis, renting is currently much cheaper than buying across all major California metropolitan areas due to high home prices and interest rates.
What is the current California housing affordability index score?
The official housing affordability index tracks at approximately 22%, meaning fewer than a quarter of California households earn the income required to buy a median priced home.
How much income do I need to buy a median California home?
To comfortably afford a median priced detached single family home in California, households generally need an annual income exceeding $204,800 to qualify for standard financing.
What are the main tax benefits of buying property in California?
Homeowners can leverage the mortgage interest deduction on up to $750,000 of debt, deduct up to $10,000 in local property taxes, and utilize capital gains exclusions upon resale.
How do low rental yields affect the rent vs buy decision?
Low rental yields mean that buying a home costs significantly more than renting it. This metric signals that renting provides superior short term financial flexibility in that specific market.
Can I deduct all of my California property taxes on federal returns?
No, the federal State and Local Tax (SALT) deduction imposes a strict maximum cap of $10,000 per year for combined property, state income, and sales taxes.
How long should I stay in a California home to justify buying?
Real estate experts generally recommend a minimum timeline of five to seven years to successfully offset upfront closing costs, moving fees, and early loan interest.
Does renting protect me against California real estate inflation?
No, renting exposes you to ongoing rent hikes. Buying a home with a fixed rate mortgage locks in your base monthly housing payment, providing long term structural stability.
What is equity building and how does it create wealth?
Equity building is the gradual accumulation of financial value in a property through a combination of monthly principal loan paydowns and organic market price appreciation over time.
Are condominiums more affordable than single family homes in CA?
Yes, data shows approximately 32% of California households can afford a median priced condo, which requires a lower qualifying income compared to traditional detached single family residences.